Every business starts with a single step forward.
You have a dream and a plan, the funds from your SBA loan can make it happen.
Behind every SBA loan is a partnership. A borrower with the drive to build something, and a lender willing to invest in that vision. It takes someone believing in a plan enough to help fund it, and someone willing to put in the work to see it through. That partnership is what turns dreams into working businesses, one opened door at a time.
While there are some moving pieces in the SBA process that are simply outside your control, taking care of your life insurance requirement early is the most effective step you can take to prevent the single most common administrative delay in releasing your funds.
CLOSING STARTS SOONER THAN YOU THINK!
Smooth closings aren’t about luck—they’re about preparation.
Common Causes of Delays:
- Insurance policies (especially life insurance)
- Landlord documents (subordination agreements, estoppels)
- Lease updates or extensions
- Payoff and good standing letters
- Entity and formation documents
The borrowers who close efficiently tend to:
- Start early on third-party requirements
- Stay organized with financial updates
- Act quickly when lenders request documents
- Communicate openly about deal changes
- Prioritize long-lead items like life insurance
The Most Avoidable Bottleneck: Your Life Insurance Mandate
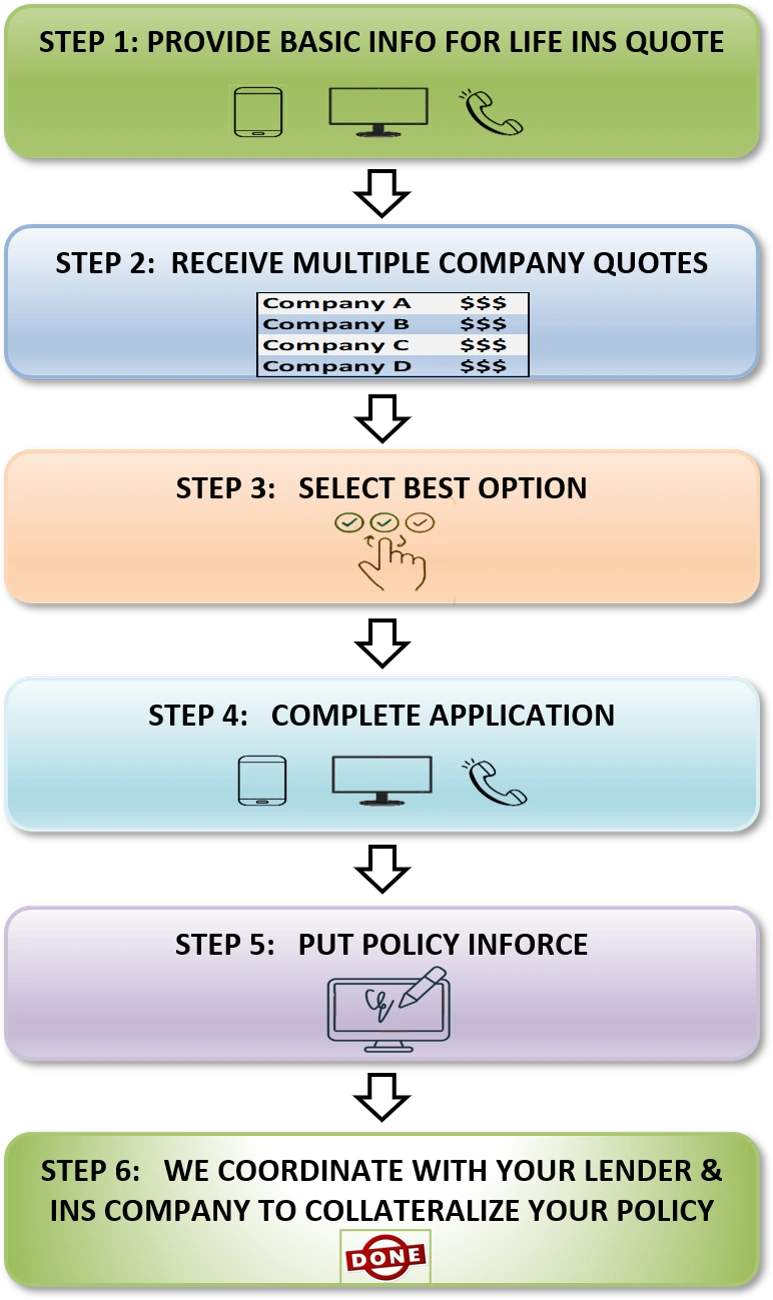
Here’s how we help you clear this requirement in days, not weeks:
- Select a Rapid-Issue Policy: We fast-track your coverage using "no-exam" term policies that can be approved instantly to 48 hours.
- Match Your Exact Loan Terms: We work with your lender to structure the policy face value and duration to perfectly satisfy your lender’s compliance guidelines on the first try.
- Handle the Carrier Paperwork: Our team works directly with the insurance provider's home office to execute and return the official collateral assignment form your lender requires to fund your loan.
DON'T LET LIFE INSURANCE DELAY THE OPENING OF YOUR BUSINESS
With 20+ top rated carriers and 85+ years of experience, we'll find you the right coverage at the best price.
DON'T PUT IT OFF ...
Request Your Life Insurance Quote TodayFrequently Asked Questions
What if I cannot qualify for life insurance?
If you cannot qualify for life insurance due to health reasons, you can request an uninsurable waiver from your lender. The SBA may allow lenders to waive life insurance requirements if a principal is deemed uninsurable, provided you supply official denial letters from insurance underwriters and pledge alternative business or personal collateral to reduce the lender’s risk.
Do I have to have a medical exam?
Not always. Many carriers now offer non-medical underwriting, and some can even deliver an instant decision. Whether you qualify depends on your current and past health history, which is exactly why working with a broker like Shadow Lake matters. We have access to multiple carriers and can identify which ones are likely to offer that path for your specific situation.
How much life insurance do I have to have?
By SBA guidelines, you only need enough life insurance to cover the "collateral gap", which is the difference between your total loan amount and the value of your other pledged assets (like real estate or equipment).
However, because life insurance is highly affordable and requires no complex property appraisals, most borrowers choose to insure the entire loan amount. Securing a policy for the full loan value satisfies lenders instantly, eliminates tedious asset-valuation math, and ensures your family is fully protected from business debt.
What kind of life insurance do I have to have?
The SBA does not require a specific type of life insurance; you can use either Term or Permanent (Whole/Universal Life) coverage. However, there is a strict timeline rule: if you use a Term policy, the policy's term length must match or exceed the lifespan of your loan (e.g., a 10-year term policy for a 10-year working capital loan).
Which one should you choose?
Term Life (Most Common): Because it is the most affordable and fastest to issue, the vast majority of SBA borrowers choose a simple level-term policy to satisfy the lender's requirements quickly.
Permanent Life: You can assign an existing permanent policy if you already have one, but buying a new permanent policy solely for a loan can slow down your closing due to more complex underwriting and higher costs.
What is buy-sell coverage?
Buy-sell coverage is a separate policy, entirely distinct from the insurance securing your SBA loan, used when a business has multiple partners. It provides the immediate cash needed for the surviving business partner(s) to buy out a deceased partner's shares from their heirs or estate.
Still Have Questions?
Contact Us TodayWe Are Here to Help
Christopher Carrigan
Partner
Licensed in all 50 states
Michael Huffman
Sr. Brokerage Manager
Licensed in all 50 states
Brook Carrigan
Life & Health Insurance Specialist
Licensed in all 50 states
Scott Tobin
Risk Analyst
Anna Carrigan
New Business & Contracting
Nick Apostolico
Insurance Specialist
Licensed in all 50 states
Jenny Tobin
Human Resources
Jackson Sobocinski
Brokerage Manager
Nico Chavez
Brokerage Manager